Report
No Data Yet

Lumentum Holdings outran every other member of the S&P 500 on Wednesday, finishing ahead of optical-component peers Coherent and Corning in a session whose percentage moves were never disclosed. The dispersion put the three networking names in a clear ranking: Lumentum first, Coherent close behind, Corning further back. No gains, trading volumes or company-specific announcements accompanied the move, leaving the relative order as the only confirmed fact of the session. Lumentum closed at $838.96 on Sept. 15, giving it a market capitalization of $75.25 billion, according to data cited by Parnassus Investments in its second-quarter 2026 investor letter. The shares have traded between $144.52 and $1,085.68 over the past 52 weeks and are up 439.98% over the past year, a run that has made the stock one of the largest single-year gainers in the index. That scale is what makes a one-day leadership change worth watching. A stock with a $75.25 billion valuation needs substantial flow to move a full percentage point, so a top-of-index finish implies either concentrated buying or an unusually thin tape. Neither was confirmed. ## Hedge fund ownership slips even as the stock climbs Positioning data runs against the price action. Hedge fund portfolios holding Lumentum fell to 111 at the end of the second quarter from 123 in the prior quarter, according to the same Parnassus letter. The decline in institutional holders while the stock gained 6.57% over the past month suggests the advance has been driven by a narrower set of buyers rather than broad accumulation. Parnassus framed the holding in structural terms. "Lumentum Holdings Inc. offers exposure to a key bottleneck in AI infrastructure, optical networking, as rising data demand drives a shift away from copper-based systems," the fund wrote in the letter. "Its components enable faster, more efficient data transfer and benefit from strong competitive advantages, including deep technical expertise and high switching costs once embedded in customer platforms." That thesis applies to Coherent and Corning as well, which is why the intraday split matters. If demand for optical components tied to AI data-center build-outs were the driver, the three names would be expected to move together. Wednesday's ordering implies stock-specific flow instead. Traders pointed to three candidate explanations, none confirmed: single-session rotation into the index's strongest momentum name, index or fund rebalancing activity, and residual positioning around the AI infrastructure trade. Without disclosed volume or a company filing, the cause cannot be established. The read-through is limited. Lumentum's move says nothing verifiable about Coherent's or Corning's order books, and a single session of relative performance carries no information about the durability of the optical-networking demand cycle. What it does show is that the market is willing to pay a premium for the purest exposure to the optical bottleneck, and that Coherent and Corning are being treated as adjacent rather than equivalent. For investors, the practical question is whether the dispersion persists. A repeat of Lumentum leading the group, particularly with volume confirmation, would suggest the market is repricing the three names on different demand curves. A reversal back toward Coherent and Corning would indicate Wednesday was flow, not fundamentals. Lumentum's next quarterly report is the first scheduled event that can settle the question. This article is for informational purposes only and does not constitute investment advice.

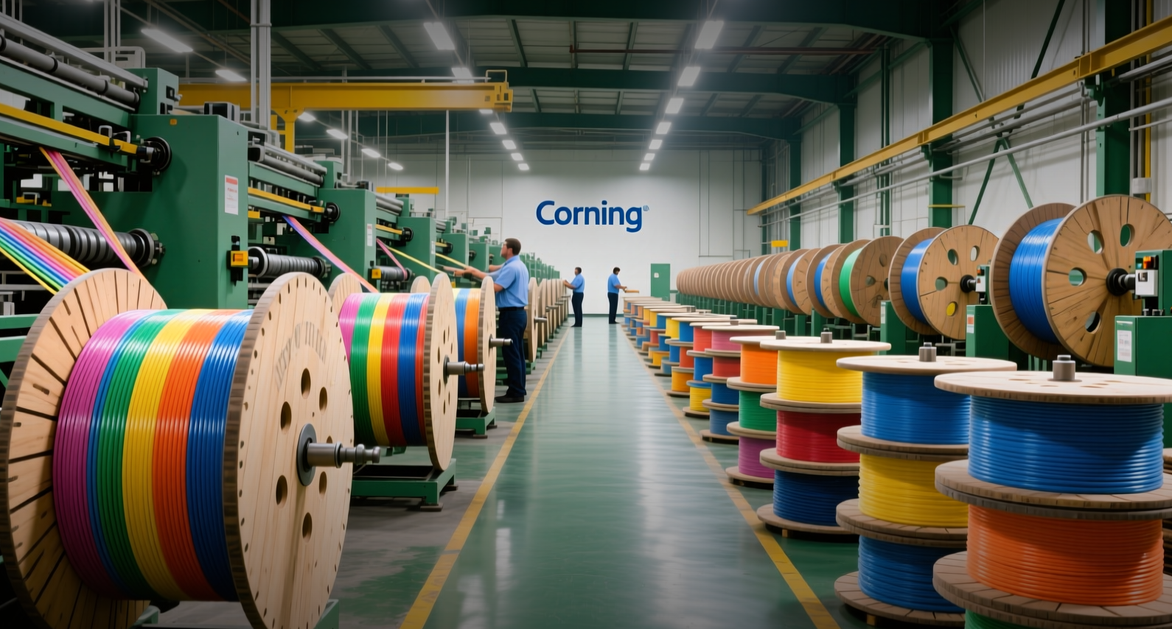
Corning shares jumped more than 7.5 percent to $165.88, their highest intraday level since Aug. 17, after Verizon signed a multi-billion dollar agreement to buy more than 80 million miles of high-density optical fiber and connectivity solutions from 2027 through 2032. "Securing this volume of fiber allows us to continue building the network of the future at an unprecedented scale," Kyle Malady, CEO of Verizon Business, said. "We are deploying a single, converged architecture that unites mobile connectivity and broadband into one seamless experience for millions of families and businesses, while simultaneously building the high-capacity, low-latency backbone AI hyperscalers demand." The supply agreement supports Verizon's push toward 40 million to 50 million broadband passings, expanding fiber-to-the-home and local business connectivity across U.S. communities. The same multi-use fiber foundation will carry AI traffic between data centers through Verizon's AI Connect strategy, which deploys ultra-dense cables across major long-haul corridors to directly connect data center facilities. The deal extends a roughly 30-year commercial relationship between the two companies and gives Corning's Optical Communications segment a defined multi-year revenue stream. Corning will expand its U.S. manufacturing footprint to meet the supply requirements, deploying products including its Contour Flow Cable, which packs more optical fiber into existing conduit pathways and maximizes the value of Verizon's infrastructure investments. The agreement comes as hyperscalers including Amazon Web Services pour capital into AI infrastructure, driving demand for high-capacity, low-latency connectivity between data centers. **Converged Architecture Reshapes Fiber Demand** The Verizon deal reflects a structural shift in telecom infrastructure spending: the same fiber networks serving residential broadband are increasingly carrying AI traffic between data centers. Verizon's approach connects cell towers, enterprise data centers, and residential neighborhoods to the same high-capacity backbone, collapsing what were previously separate network builds into one converged grid. For customers, this means continuous connectivity whether at home or on the move, with the same infrastructure supporting consumer broadband, mobile backhaul, and AI data center interconnectivity. For Corning, the contract provides a revenue anchor for its Optical Communications business, a key growth driver as telecom operators and cloud providers expand network capacity. Scaling U.S. manufacturing for the Verizon deal also positions Corning to serve other carriers pursuing similar converged architectures, potentially opening additional long-term supply opportunities. Mike O'Day, senior vice president and general manager of Corning Optical Communications, said the partnership shows that generative AI and broadband expansion are part of the same opportunity. "Corning is proud to build on our 175-year legacy of supporting our customers' growth with breakthrough innovations that we manufacture at scale here in the United States," he said. **Revenue Visibility Through 2032** The agreement gives Corning investors a defined earnings trajectory through the end of the decade, with the deal structured to enable Corning to scale production capacity ahead of the 2027 delivery start date. The contract also signals that fiber optic suppliers stand to benefit from the convergence of consumer broadband expansion and AI data center interconnectivity — two demand streams previously viewed as separate markets. For the broader fiber optic supply chain, the deal suggests sustained demand for high-density cable products as carriers upgrade networks to handle both consumer traffic and AI workloads. Corning shares, which had traded at their highest level since Aug. 17, now carry a revenue window from the Verizon contract running from 2027 through 2032. The deal's multi-billion dollar scale reflects the magnitude of infrastructure investment required to support the AI era, with fiber as the physical foundation connecting data centers, businesses, and homes. This article is for informational purposes only and does not constitute investment advice.

A combined $2 billion in fresh capital from four American firms will flow into South Korea's chip materials, semiconductor equipment, and offshore wind industries, Seoul's trade ministry confirmed Friday, marking one of the largest recent U.S. direct investment packages in the country's strategic sectors. The commitments were announced at an investment declaration ceremony in the United States organized by the Ministry of Trade, Industry and Energy and KOTRA, the state trade promotion agency. The investing firms include Air Products, Corning, and Axcelis Technologies, with facilities planned for Pyeongtaek in Gyeonggi Province, according to the ministry. The investments target segments where Washington and Seoul have coordinated policy to secure critical supply chains. The semiconductor portion extends a pattern of deepening U.S.-South Korea industrial integration that has accelerated as both governments seek to reduce reliance on concentrated Asian manufacturing hubs for advanced chips and related inputs. For South Korea, the inflows reinforce its position as a primary destination for allied semiconductor investment. The country hosts fabrication plants operated by Samsung Electronics and SK Hynix, the world's two largest memory chip makers, and has become a focal point for U.S. firms seeking proximity to advanced manufacturing capacity. The new commitments add to a pipeline of foreign direct investment that Seoul has courted through tax incentives and streamlined permitting for high-tech industrial sites. The energy component, which includes offshore wind, aligns with South Korea's renewable energy targets and its push to attract foreign capital for clean power infrastructure. Air Products, a major industrial gas supplier, brings expertise in hydrogen and clean energy technologies that could support both semiconductor fabrication processes and South Korea's decarbonization goals. The investment announcement carries implications for listed companies in both markets. South Korean semiconductor materials and equipment suppliers could see increased demand as U.S. firms establish local operations, while the investing U.S. companies gain strategic footholds in Asia's most advanced chip manufacturing base. The commitments also reflect continued confidence in South Korea as a manufacturing destination despite broader global trade frictions. The timing is notable given ongoing coordination between Washington and Seoul on semiconductor policy. The United States has restricted certain advanced chip exports to China, while South Korea has balanced its alliance obligations with its substantial trade relationship with Beijing. Investments of this scale suggest the two governments are moving toward deeper integration in critical technology supply chains. The fourth company involved in the investment package has not been identified in available reporting. The ministry's announcement did not specify a timeline for when the facilities would begin operations or the exact allocation of the $2 billion across the three sectors. For investors, the key question is execution. Foreign direct investment commitments of this nature can take years to materialize into operational facilities, subject to permitting, financing, and market conditions. The semiconductor equipment and materials segments are particularly sensitive to the cyclical demand environment for chips, which has shown signs of recovery after a prolonged downturn. South Korea's semiconductor exports have been a critical driver of its economic growth, and the government has made attracting foreign investment in the sector a policy priority. The country's trade ministry has actively courted U.S. and European firms with investment incentives, positioning South Korea as a reliable manufacturing partner for allied nations seeking supply chain diversification. This article is for informational purposes only and does not constitute investment advice.

The Nasdaq Composite fell 1.28% at the September 1 open, leading a broad US equity decline as optical communications and memory chip stocks came under pressure. The move coincided with two catalysts: "Big Short" investor Michael Burry's disclosure of new short positions against AI and semiconductor names, and profit-taking in optical stocks after Corning surged 15.67% on Monday to a record high. The Dow Jones Industrial Average slipped 0.64% and the S&P 500 lost 0.70%. Corning and Marvell Technology each fell more than 3%, while Intel and SanDisk dropped over 2%. Western Digital, Seagate Technology, SK Hynix, and Micron Technology all declined more than 1%. The declines extend a volatile stretch for semiconductor equities, where Marvell has dropped roughly 10% since its earnings report despite a 37% jump in second-quarter sales to $2.74 billion. Fervo rose more than 7% after signing a roughly 400-megawatt geothermal power supply agreement with Google, the latest clean-energy deal tied to AI data center demand. The selloff in chip and optical names tracked weakness in pre-market futures, where the Nasdaq 100 had already slipped 0.39% and S&P 500 futures fell 0.17%. Burry, the investor who inspired "The Big Short," disclosed short positions against Nvidia, Applied Materials, and the iShares Semiconductor ETF in a Substack post, adding to pressure on a sector already facing class-action lawsuits against Samsung, SK Hynix, and Micron. Corning's decline followed two days of profit-taking after the glassmaker jumped 15.67% on Monday to a historic high. Marvell, which fell about 10% after its earnings report last week, continued to slide even as it guided to third-quarter sales of $3.15 billion, up 50% year over year. Analysts have noted the Google agreement could drive up to $20 billion in annual product sales, though guidance implies a more modest $6 billion in incremental revenue. The selling extended across assets. Bitcoin traded near $58,597, below the $59,000 mark, while spot gold slipped to $3,990 an ounce and WTI crude fell to $68.69 a barrel, its lowest since February 27. The US dollar index edged higher to around 101.34. Capital continues to flow into AI infrastructure even as chip equities wobble, with SoftBank completing a $10 billion follow-on investment in OpenAI and Japan approving 387.3 billion yen in subsidies for domestic AI research. Investors now turn to the June ADP private employment report, due at 8:15 a.m. Eastern, and a speech by Federal Reserve Chair Warsh at the European Central Bank's forum in Sintra, Portugal, at 9 a.m. The data and remarks will shape expectations for Friday's nonfarm payrolls report, where the market consensus calls for 115,000 jobs added and an unemployment rate of 4.3%. This article is for informational purposes only and does not constitute investment advice.

**Rising bond yields are forcing investors out of high-valuation AI and growth names, with the 10-year Treasury yield near 4.73% pressuring the sector that led this year's rally.** AI hardware names including Sandisk, Corning, and Intel fell on Sept. 1 as investors dumped risk assets, extending a rotation that has punished expensive growth stocks since late August. The selloff tracked a global climb in government bond yields, with Japan's benchmark 10-year JGB yield touching 3% for the first time since 1996 and the U.S. 10-year Treasury yield holding near 4.73%. "The move in yields is the single biggest variable for equity multiples right now," said Priya Mehta, equity strategist at a New York-based asset manager. "When the risk-free rate rises, the present value of earnings five years out shrinks, and that hits the AI trade hardest." The pressure was broad. Marvell, Robinhood, Dell, and Novartis also declined as risk-off positioning swept through equities, according to Barron's. The pattern mirrors fund-flow data showing investors pulled $22.33 billion from U.S. equity funds in the week through Aug. 26, the largest outflow since March, with large-cap funds absorbing $24.73 billion in withdrawals while mid-cap and small-cap strategies drew inflows. **Yields Reshape the Growth Trade** The catalyst is a convergence of macro pressures. Federal Reserve Chair Kevin Warsh's Jackson Hole comments emphasized inflation risks, pushing U.S. yields higher and leaving investors to price a possible September rate increase. Persistent inflation, elevated government borrowing, and Brent crude above $90 following renewed Middle East tensions have compounded the move. Higher yields raise the discount rate applied to future earnings, making growth shares whose valuations depend on profits years ahead more vulnerable. The transmission is visible across markets: Japan's Nikkei 225 closed at 66,215.34, down 0.15%, even as the broader TOPIX rose 0.62% to 4,181.86 for a ninth straight gain, as investors rotated from AI and semiconductor names into utilities, banks, and trading houses. U.S. bond funds attracted $7.12 billion in the latest week, extending an inflow streak to 19 consecutive weeks, while global bond funds took in $10.25 billion. The contrast with equity outflows signals a defensive tilt as investors weigh whether yields can stabilize. **What's at Stake** The trajectory of the 10-year Treasury yield now determines whether the AI de-rating deepens. If yields push clearly above 4.75%, valuation compression across semiconductor and AI infrastructure names could persist into the September Federal Reserve meeting. If they stabilize, investors may treat the level as a new equilibrium and rotate back into growth. The yen near 159.80 to the dollar and oil in the low-$90 range add to the cross-asset pressure, keeping inflation expectations elevated and complicating central bank policy. U.S. jobs data and next week's producer and consumer price figures will be the next catalysts, with the Fed's September meeting and the Bank of Japan's Sept. 17-18 decision shaping whether the yield run-up extends. This article is for informational purposes only and does not constitute investment advice.

**Global bond yields are climbing to multi-year highs, squeezing equity valuations and pressuring tech-heavy futures.** U.S. stock futures slipped Tuesday as a global bond selloff pushed the 10-year Treasury yield to a near 20-month high of 4.78 percent, pressuring equity valuations. Dow futures fell 0.24 percent, S&P 500 futures dropped 0.17 percent, and Nasdaq 100 futures slid 0.39 percent, with semiconductor and memory chip stocks leading the decline. "The macro mix is turning more challenging for duration and risk assets," said Wee Khoon Chong, APAC Macro Strategist at BNY. "Hawkish monetary policy, renewed geopolitical and inflation risks, and rising fiscal concerns are converging to maintain the upward pressure on global term premiums and long-end yields." The yield surge is global in scope. Japan's 10-year JGB yield is closing in on 3 percent, a level not seen for a generation, while German and French long bond yields hit 15-year highs Monday. Bund futures made a new 15-year low in Asia trade Tuesday, and French OAT futures traded at their lowest since launching in 2012. **Chip stocks weigh on Nasdaq futures** Semiconductor weakness was the primary drag on tech futures. Micron Technology fell over 2 percent pre-market, SanDisk dropped nearly 4 percent, and Seagate Technology slipped nearly 1.5 percent, following "Big Short" investor Michael Burry's disclosure of new short positions on AI and semiconductor stocks. The optical communications sector also weakened, with Corning down 2.3 percent after profit-taking following a 15.67 percent surge Monday, while Marvell Technology fell about 1.6 percent. The bond selloff is being reinforced by geopolitical and inflation pressures. Brent crude topped $91 a barrel in Asia trade after renewed U.S.-Iran fighting, while Europe's benchmark gas price closed at a more than 3-1/2-year high Monday. Wheat prices are trading near three-year highs as Russia-Ukraine fighting escalates. **Rate hike expectations build** Markets are pricing an interest rate hike in New Zealand on Wednesday and an increase in Europe next week. Hikes this month in the U.S. and Japan are at better-than-even odds, after Fed Chair Kevin Warsh signaled policymakers could move if price pressures fail to ease. U.S. jobs data on Friday could open the door to a rate hiking cycle starting as soon as this month. The yield move has already rippled through Asian equities. Japan's Nikkei dipped 0.2 percent in early trade, and the Hang Seng fell 0.7 percent, with the tone set by the lackluster debut of clothier Shein Global, which traded just below its IPO price. The fast-fashion retailer has been hit by tariff and duty changes in the U.S. and Europe that have eroded a key pillar of its low-cost business model. Because the rise in borrowing costs has been global, it has offered only limited support to the U.S. dollar. The euro was steady at $1.1619, and the yen traded at 159.76 to the dollar. Preliminary inflation figures are due in Europe later Tuesday. This article is for informational purposes only and does not constitute investment advice.

**Union labor groups are threatening to withhold political support from candidates who oppose data-center construction, opening a new front in the fight over AI infrastructure ahead of the 2026 midterm elections.** Union labor groups representing electricians and steamfitters are threatening to withhold political support from candidates who oppose data-center construction, as the AI infrastructure build-out collides with a nationwide backlash over electricity, water and tax breaks. "We are dependent on these jobs," Sidney Bonilla, treasurer and business manager of Steamfitters UA Local 602, said. The union, whose members install mechanical piping systems across Virginia, Maryland and Washington, D.C., circulated a memo drawing a "clear line" against politicians who oppose the facilities, calling it "an existential moment for Local 602." IBEW Local 26 electricians worked 28 million hours last year, double the 14 million a decade earlier, said Don Slaiman, the union's political coordinator. In Kansas, an HVAC and railroad workers union broke decades of precedent to endorse Republican state Sen. Ty Masterson for governor, partly because the Democratic candidate opposed construction. The AFL-CIO's affiliated unions in June passed a resolution calling for guardrails on AI and data centers while acknowledging the facilities employ tens of thousands of union members. The political friction threatens to slow approvals for projects that OpenAI, Anthropic and other AI companies need to support more powerful models. President Trump has continued to back the build-out, saying data centers mean "jobs, income and lower taxes," but governors in New York, Pennsylvania and Texas have tightened oversight or halted approvals as midterm elections approach. ## Backlash to the Backlash The union mobilization marks a counterweight to a resistance movement that has grown so broad it now cuts across party lines. Conservative farmers in rural Nebraska have joined the state Sierra Club chapter in opposing development, while a July Fox News poll found most registered voters oppose building a data center in their area, including 60 percent of Republicans and 53 percent of MAGA voters. In Cass County, Nebraska, officials approved a 12-month moratorium on data-center development, potentially freezing energy company Tenaska's plans to option more than 1,300 acres along Highway 75. Land that typically sells for $10,000 an acre has drawn developer offers of four times that or more, tempting farmers even as soybean exports decline in Trump's tariff fight with China. New Mexico's Project Jupiter, a $165 billion Oracle complex near the Mexican border, has triggered an emergency petition to the state Supreme Court over water rights. The state's largest reservoir stands at 1.3 percent capacity, and the court halted authorization to use water from a new well until the legal fight concludes. Oracle has pledged $50 million for water and wastewater systems and claims the project would generate $4.7 billion in taxes and create more than 7,000 construction jobs. ## The Jobs Math Behind the Fight Union leaders argue the construction boom represents a once-in-a-generation opportunity for skilled workers. "This is a once-in-a-generation opportunity to really get in the upper-middle class," Slaiman said. Electricians are showing up at public hearings and planning-commission meetings to speak in favor of projects, sometimes staying past midnight. Mike Gage, president of the Nebraska State AFL-CIO, said data centers can create construction jobs and longer-term positions, noting a facility built decades ago in Council Bluffs, Iowa, still employs about 60 people. Heather McKenzie, who works in labor relations in Lincoln, said more data centers could slow the exodus of skilled young people leaving the state. The build-out has also pushed Meta Platforms and other tech companies to invest in training skilled workers. OpenAI, Alphabet's Google and Microsoft have partnerships with unions and have highlighted worker shortages as a key bottleneck for the U.S. in the AI race. Corning, the 175-year-old glass manufacturer, is partnering with Nvidia to build three optical-manufacturing facilities in North Carolina and Texas, a project expected to create more than 3,000 jobs and expand U.S. optical-fiber capacity tenfold. The political terrain remains treacherous for both parties. In Wisconsin, Democratic gubernatorial candidate David Crowley has won support from some building trade unions while being attacked by Republican Rep. Tom Tiffany for being in the pocket of labor groups and tech companies. Wyoming Secretary of State Chuck Gray, a Republican running for an open House seat, has pledged to halt construction, saying "if Silicon Valley wants to build their liberal empire, they can do it somewhere else." Todd Vachon, director of the Labor Education Action Research Network at Rutgers University, said the AFL-CIO faces a difficult balancing act between unions that benefit from construction and white-collar unions wary of AI's impact on jobs. Politicians who need labor support may be forced to back highly unpopular data centers. "How's that going to come on Election Day?" Vachon said. For investors, the outcome carries direct implications for the pace of AI infrastructure spending. Microsoft, Meta, Google and Amazon have committed tens of billions of dollars in annual capital expenditures to data-center construction, and any slowdown in approvals could push back project timelines and raise costs. Trump's continued support provides a federal tailwind, but state-level moratoriums and permitting freezes in New York, Texas and Pennsylvania could force hyperscalers to concentrate new builds in friendlier jurisdictions. This article is for informational purposes only and does not constitute investment advice.

Corning's Optical Communications segment sales rose 32 percent year over year to $2.07 billion in the second quarter, driven by AI data center demand. Corning said its current growth is primarily driven by Scale-Out infrastructure, where operators connect large numbers of servers and GPUs using high-bandwidth optical links. The expansion of generative AI is increasing the amount of high-speed optical connectivity needed inside and between data centers, fueling demand for Corning's GenAI-related enterprise products. Segment net income jumped 77 percent to $438 million. Enterprise Networks sales within the segment increased 65 percent year over year. Amazon announced a multiyear, multibillion-dollar agreement to use Corning's optical fiber, cable and connectivity solutions for U.S. data center infrastructure. NVIDIA is collaborating with Corning to expand U.S. optical connectivity manufacturing capacity. Beyond Scale-Out, Corning expects significant growth from Scale-Up systems, where high-bandwidth connections are needed between GPUs and other computing components. This represents another major growth opportunity for the company's optical connectivity portfolio in coming years. Competitors are also capturing the AI-driven optical networking boom. Amphenol's Communications Solutions revenue jumped 85 percent year over year to $5.38 billion in the second quarter, making it the company's largest business segment. Ciena's Optical Networking revenue rose to $1.10 billion from $773.6 million a year earlier, and the company expanded its WaveLogic 6 Extreme platform to 110 customers, adding 20 new users in the fiscal second quarter. Ciena raised its fiscal 2026 revenue outlook to $6.3 billion, plus or minus $100 million, representing roughly 32 percent growth at the midpoint. The company is also deploying WL6e on ION Network's new submarine cable system spanning more than 2,000 kilometers between Jakarta and Singapore, scheduled to go live toward the end of 2026 with up to 288 Tb/s of end-to-end capacity. The deployment uses Ciena's Layer 0 control-plane capabilities to improve service availability and operational efficiency. Nokia's AI and Cloud revenue more than doubled year over year in the second quarter, with order intake reaching 2.8 billion euros, reflecting broad demand across Optical Networks and IP Networks. The planned divestiture of Nokia's Fixed Wireless Access CPE business simplifies its portfolio and allows greater investment in higher-growth areas such as AI networking and optical technologies. The AI-driven demand for high-speed optical connectivity represents a structural growth trend for Corning and the broader optical components sector. Investors will watch Corning's next earnings report for updated guidance on Scale-Up system adoption and segment margin expansion. This article is for informational purposes only and does not constitute investment advice.

US optical stocks fell broadly in pre-market trading, with Coherent down over 5% and Lumentum nearly 5%, as rising Treasury yields pressured the AI hardware trade. UBS analyst Timothy Arcuri, in a note that flagged continued strength in Nvidia's Blackwell systems and an expected ramp of the Rubin platform as tailwinds for Marvell's optical products, said rising yields raise the discount rate applied to distant future earnings, compressing valuations most for stocks whose cash flows sit furthest in the future. Marvell Technology dropped 6% to $219.28 in pre-market, giving back part of a 176% year-to-date run, while Corning fell nearly 4%. Broadcom slipped 2% to $384.59 and Nvidia eased 2% to $220.22. The iShares Semiconductor ETF slid 4% to $537.48, with the group's most extended names bearing the brunt of the selling. The 30-year Treasury yield hit 5.31% on Monday, a fresh multi-year high that pressures every long-duration growth name. The selloff extended a rotation out of AI infrastructure names after Anthropic told investors its annualized revenue reached $65 billion at the end of July, below the $80 billion-plus whisper figures circulating in Silicon Valley. A Wall Street Journal analysis found nine top tech companies held some $3 trillion of off-balance-sheet commitments, mostly related to AI, about triple what they owe under outstanding leases and long-term borrowings. That capex is exactly what feeds the optics supply chain, making the group sensitive to any sign of a slowdown in AI infrastructure spending. Lumentum, up 163% year to date, and AXT, up 487% over the past month, gave back the most after leading the group higher on reports of indium phosphide shortages. Fabrinet plunged 20% despite record fiscal fourth-quarter revenue of $1.316 billion, up 45% year over year, as investors read its guidance as conservative for a stock that had run hard. The rotation is a positioning story as much as a fundamental one. The stocks that ran hardest into the session are giving back the most, with Lumentum still up 19% over the past week and Corning up 98% year to date. Nothing has changed about the indium phosphide supply picture in 24 hours, yet the group is trading as if the thesis broke. If the 30-year gives back some of its move, expect the optical group to stabilize; if yields press higher, the profit-taking has more room to run. Marvell reports fiscal third-quarter earnings in nine days, a scheduled event that could reset expectations for the group. This article is for informational purposes only and does not constitute investment advice.

Memory chip stocks slid as much as 5 percent in premarket trading Monday as Samsung Electronics' record shareholder-return plan fell short of expectations, triggering profit-taking in one of 2026's most crowded semiconductor trades. "This feels less like a fundamental reset and more like a positioning unwind," Daniel O'Regan, an analyst at Mizuho, said. "AI spending, data-center demand and adoption remain intact." SanDisk fell 5.39 percent to $1,509.80, while Micron Technology dropped nearly 4 percent and SK Hynix lost about 3 percent. AMD slipped 2 percent to $463.08 and Intel fell 2 percent to $88.30. In Seoul, Samsung plunged 9 percent after its plan to return between 90 trillion won and 110 trillion won to shareholders in 2026 lacked immediate buyback commitments. The selloff lands ahead of Nvidia's earnings Wednesday and the Federal Reserve's Jackson Hole gathering, tests that will determine whether AI infrastructure spending can sustain the memory pricing that has driven Micron's gross margin to 84.6 percent. **Samsung's payout plan triggers a sector-wide trim** Samsung's 9 percent plunge gave investors a reason to take profits after a powerful rally. The Korean chipmaker authorized a 2026 shareholder payout of 90 trillion won to 110 trillion won, including about 30 trillion won in third-quarter dividends, with the remainder to be set in January 2027. JPMorgan analysts said the absence of an instant buyback cancellation and an unchanged return figure could lead to short-term disappointment. The move rippled across the memory complex. Coherent fell about 5 percent and Lumentum 4.5 percent, while Corning and Seagate each slipped around 3 percent. The weakness extended to Asia, where SK Hynix lost about 3 percent in Seoul. **A crowded trade meets stretched expectations** Memory stocks have been among the biggest AI winners, powered by data-center investment, tight supply and stronger pricing. Micron reported fiscal third-quarter revenue of $41.46 billion with a GAAP gross margin of 84.6 percent and net income of $28.24 billion, up from $9.30 billion in revenue a year earlier. SK Hynix has more than doubled in 2026. That success made the trade heavily owned. When positions become crowded, investors do not need negative fundamental news to sell — a weaker risk backdrop can be enough. Nasdaq-100 futures were down about 0.6 percent Monday as investors trimmed technology exposure. Jensen Investment Management managing director Allen Bond said memory and storage companies are "the most exposed to that incremental supply and demand" from continuing data-center construction. VistaShares investment strategist David Fetherstonhaugh characterized the weakness as macro-driven rather than evidence of deterioration in the underlying memory story. **Nvidia's report becomes the fundamental test** The underlying memory thesis remains stronger than Monday's share-price action suggests. Bank of America's Vivek Arya reiterated a Buy rating on Micron and raised his target to $1,550, arguing Wall Street underestimates the company's longer-term earnings power. The 47-analyst consensus remains Strong Buy with an average target of $1,515, implying about 57 percent upside from Friday's close of $966.78. A longer-dated supply question also looms. The parent of Yangtze Memory Technologies seeks to raise 33 billion yuan ($4.9 billion) through a Shanghai listing to fund production upgrades, adding potential NAND capacity even as U.S. trade restrictions limit YMTC's reach. Micron shares, trading near record levels after a 2026 surge, face their next test when Nvidia reports Wednesday and Marvell Technology follows Thursday. Any indication that AI infrastructure investment remains strong could help stabilize the semiconductor trade; a miss would deepen the pullback in a sector where expectations leave little room for disappointment. This article is for informational purposes only and does not constitute investment advice.