Edgen AI operates independently of, and is not controlled by Aspen Digital Financial Limited.
Xi lands in Washington with $30 billion tariff framework on the table
 Edgen Stock·Sep 24 2026, 00:09
Share to
Share to
Copy link
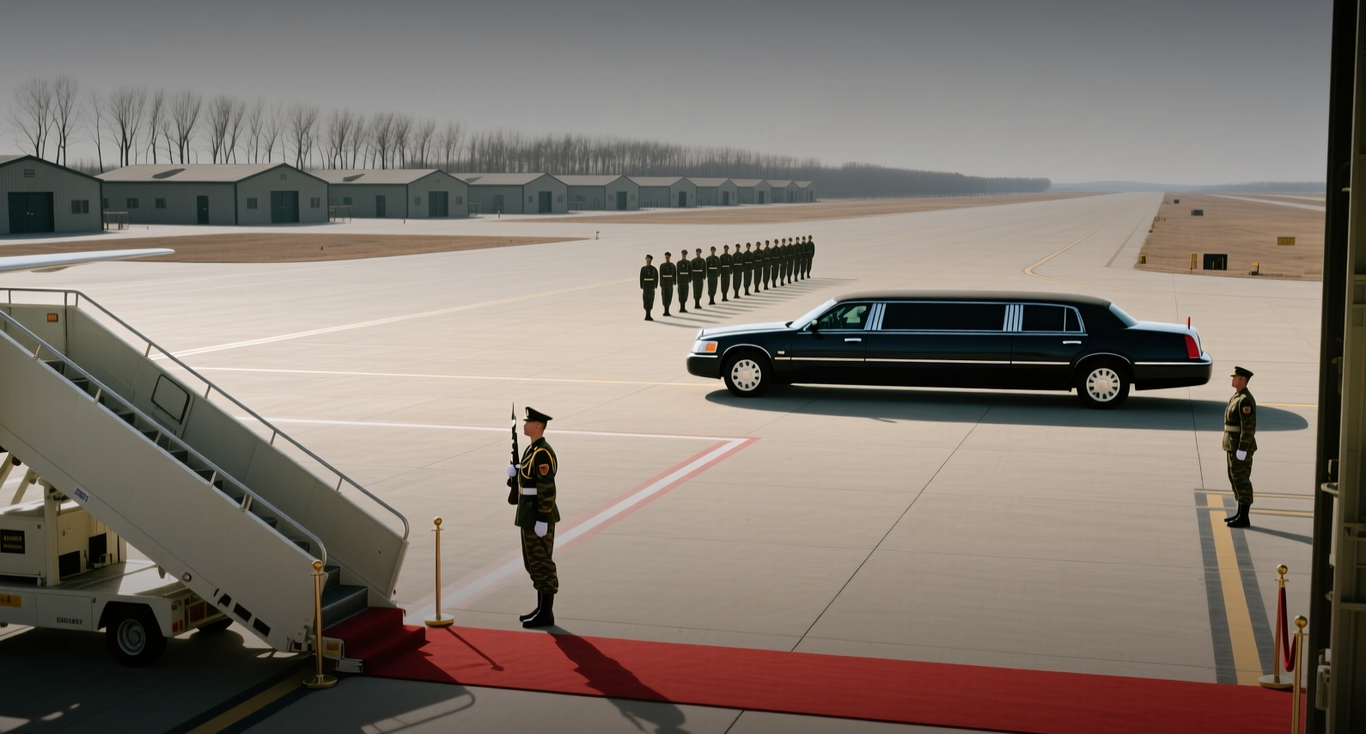
[1] Xi Jinping Arrives in Washington for State Visit to the United States (https://wallstreetcn.com/livenews/3169934 ...)[2] Xi Jinping arrives in Washington as Trump gives rare airport welcome to kick off US state visit: Top developments (https://timesofindia.indiatimes.com/world/us/ ...)[3] Xi arrives in US for three-day state visit (https://www.yahoo.com/news/politics/articles/ ...)[4] Xi Jinping’s Visit to Washington: What It Means for US-China Relations (https://moderndiplomacy.eu/2026/09/21/xi-jinp ...)[5] Trump is giving China’s Xi a warm welcome. But criticism is loud on Capitol Hill (https://apnews.com/article/republicans-democr ...)
Related News
Sep 23 2026, 23:55
L.A. pins 4,495 film jobs on Paramount merger concessions
Rob Bonta holds the leverage, and Los Angeles knows it. The California attorney general is trading away an antitrust lawsuit for enforceable conditions on a $111 billion studio combination, and the county's own analysts calculate that 4,495 direct film and television job-years sit in the balance between 2027 and 2030, with total employment exposure near 10,360 job-years. "The question is, 'Does this have any teeth? Does this advisory board really have any sort of impact in making sure that news organizations like CNN remain independent?'" Michael Schneider, executive television editor at Variety, said of the Editorial Independence Board that Paramount has offered as a concession. "We'll just have to wait and see." Two reports, pointing in opposite directions, frame the argument. A study commissioned by the Los Angeles County Department of Economic Opportunity and produced by CVL Economics put the exposure at 4,495 direct film and television job-years and roughly 10,360 total job-years, alongside $1.26 billion in wages, $4.06 billion in business output and $547 million in tax revenue. CVL described those figures as "employment capacity at risk" rather than a layoff forecast. A separate draft from the Los Angeles County Economic Development Corp., commissioned by Paramount and leaked to Politico, projected the completed merger would add as much as $1.01 billion in economic growth over five years, while a collapse would cost the state as much as $21.2 billion a year. That draft also estimated a full corporate exit from California would eliminate between 28,990 and 57,980 jobs and cut annual output by $10.6 billion to $21.2 billion. The transaction is frozen pending an antitrust suit filed by California and 11 other states. U.S. District Judge Araceli Martínez-Olguín in Oakland has set trial for March 2. Paramount faces a tighter deadline: if the deal does not close by Oct. 1, it owes Warner shareholders roughly $7 million per day in a "ticking fee." Bonta has said he is willing to negotiate over concessions that would prompt him to drop the suit, and has complained about what he calls Paramount's under-the-table maneuvering. ## A rally, a ticking fee and a 30-film pledge Opponents gathered outside Paramount Studios on Tuesday, organized by the Block the Merger Coalition, with actors, writers and local officials pressing to halt the transaction. Burbank City Councilmember Konstantine Anthony said upward of 30,000 redundant positions could be at risk as administrative and distribution operations combine across the two companies. Actor Constance Marie framed the dispute as a labor question: "Censorship has never been good for people of color, and that is why I'm here to say this is not good, and it's not good for labor, and we're a dominant part of the labor workforce." The rally followed a settlement between Paramount owner Skydance and 12 states, California among them, in the antitrust case. Schneider said the merger now looks close to certain. "At this point, I'm not sure there's much left to block this merger," he said. "It does seem to be happening and it's going to happen in the next couple of weeks." He added that overlap between the two companies points to cost cuts before the holidays, since the fourth quarter is already underway. What the concessions are worth depends on which commitment holds. Paramount has pledged the merged company would produce 30 feature films a year for three years; an analysis of that pledge found it could generate almost $20 billion in additional U.S. economic activity and support more than 90,000 jobs nationwide. The LAEDC draft treated the 30-film commitment as a firm anchor, though no written, enforceable guarantee exists. The combined company would carry a debt overhang estimated at $79 billion to $82 billion, which raises questions about Paramount's claim that it can generate $6 billion in annual savings by selling real estate and consolidating streaming services rather than cutting staff. The LAEDC specified it did not examine the likelihood or potential impacts of consolidation after a completed merger. For Los Angeles, the concession package is the variable that decides the outcome. If Bonta secures enforceable production and employment commitments, the county's exposure stays near the low end of the CVL range and the 30-film pledge becomes the floor for local stage and crew work. If the suit proceeds to the March 2 trial and Paramount's ticking fee keeps accruing at $7 million a day, the company's stated alternative — relocating headquarters and thousands of jobs to Georgia, Tennessee or Texas — becomes a live negotiating threat rather than a hypothetical. The companies aim to finalize the merger in October. This article is for informational purposes only and does not constitute investment advice.
Sep 23 2026, 23:30
AngloGold Ashanti slides 5.6% as gold miners lag broader market
AngloGold Ashanti Ltd. closed at $98.74 on Sept. 23, down 5.6% from the prior session, a decline that ran well past the drop in the wider U.S. equity market and left the gold miner among the session's weakest large-cap precious-metals names. The move came on volume that ran above the stock's recent average, according to exchange data, with the shares finishing near the lower end of the day's range. AngloGold's fall was roughly four times the decline recorded by the benchmark index that session, a gap that points to selling specific to the gold-mining complex rather than a uniform de-risking across equities. "Gold equities had been priced for a flat-to-higher metal price, so any unwind in that trade hits the miners harder than the index," said Priya Mehta, equity market strategist covering flows and positioning. "When a single name gives back 5.6% in one session while the tape is only modestly lower, the first question is whether it is a stock-specific repositioning or the start of a sector-wide de-rating." The scale of the move is best measured against the metal itself. Spot gold has traded in a narrow band through the period, meaning AngloGold's decline was not matched by a comparable drop in the underlying commodity — the classic signature of equity-level repositioning rather than a fundamental repricing of bullion. That divergence matters because gold miners carry operating leverage to the metal price: a 1% move in gold has historically translated into a multiple of that in miner earnings, which cuts both ways when positioning reverses. Peer read-across is the next test. Newmont Corp. and Barrick Mining Corp., the two largest North American-listed gold producers, and the VanEck Gold Miners ETF (GDX) are the instruments traders watch to determine whether the weakness is idiosyncratic to AngloGold or a broad rotation out of precious-metals equities. A single-session drop in one miner, even a large one, is usually absorbed within days; a second and third session of underperformance across the group would signal that portfolio managers are cutting sector exposure rather than trimming one position. The broader market backdrop did not help. The session's index-level decline reflected a market-wide pullback, and AngloGold's underperformance against that benchmark is the number that matters for relative-performance mandates — funds benchmarked to the index lose ground on every session the stock lags, regardless of the absolute direction of the tape. For holders, the near-term question is whether $98.74 holds as a floor. AngloGold's next scheduled disclosure and the next U.S. inflation print are the two dated events that will determine whether the unwind stops here or extends into the peer group. Traders will also watch the gold price itself: a stable metal price alongside continued miner weakness would confirm the move as positioning-driven, while a falling gold price would turn a one-day unwind into a sector re-rating. This article is for informational purposes only and does not constitute investment advice.
Sep 23 2026, 23:27
Ginkgo Bioworks slides 8.4% to $8.58 in company-specific selloff
A single-session loss of 8.43% took Ginkgo Bioworks Holdings Inc. (DNA) down to $8.58 on Sept. 23, a drop steep enough to separate the synthetic-biology company from a broader market that moved far less. No company filing, earnings release or disclosed regulatory action accompanied the decline. Traders pointed to three candidate drivers rather than one confirmed cause: a de-risking wave through pre-revenue biotech names, thin liquidity in a small-cap float that magnifies order-flow imbalances, and a rates backdrop that keeps pressuring long-duration cash-burning equities. None of the three has been confirmed by the company. "Single-session drops of this size in a small-cap synthetic-biology name are usually flow, not fundamentals," said Sarah Lin, an equity analyst covering U.S. biotech at Edgen Research. "When there is no 8-K and no guidance change, the tape is telling you about positioning, not about the science." The move was company-specific in the literal sense: DNA's decline outpaced the broader market's session change by a wide margin, and no peer in the synthetic-biology group fell by a comparable amount on the same day. That divergence is the core fact of the session — a stock falling on its own weight rather than being dragged by an index. For context on scale, Ginkgo operates a foundry model that sells cell-programming capacity to partners across pharma, agriculture and industrial chemicals, a business that depends on continued capital access while programs mature. A stock trading in the single digits with a small float is structurally more sensitive to a single large seller than a large-cap peer would be. The cross-asset backdrop offered little help. Treasury yields held near recent ranges, keeping the discount rate applied to future cash flows elevated for companies that are not yet profitable, and the dollar's firm tone added a second headwind for a business with international partners. Neither moved enough on the day to explain an 8.43% single-name decline on its own. What matters next is whether a disclosure follows. Ginkgo's next scheduled corporate update is the event that would either supply the missing catalyst or confirm that the drop was positioning-driven. Until then, holders are marking a loss on a move that has no documented fundamental trigger — which cuts both ways: absent a filing, there is nothing new to price in, and absent a filing, there is nothing to stop the selling from continuing. The stock's near-term path now hinges on volume. If the decline came on above-average turnover, it points to institutional exit; if it came on thin volume, it points to a liquidity air pocket that can reverse as quickly as it formed. Neither scenario is confirmed by the data available at the close. This article is for informational purposes only and does not constitute investment advice.