Edgen AI operates independently of, and is not controlled by Aspen Digital Financial Limited.
Novo Nordisk slides 7% as $23 billion obesity target underwhelms
 Edgen Stock·Sep 21 2026, 10:56
Share to
Share to
Copy link

[1] Novo stock falls as much as 7% despite $23 billion sales target for blockbuster obesity drugs (https://www.cnbc.com/2026/09/21/novo-nordisk- ...)[2] Novo Nordisk aims to launch more than five blockbuster drugs by 2030, CEO says (https://www.msn.com/en-us/news/other/novo-nor ...)[3] Wegovy Maker Novo Nordisk Targets Several New Blockbuster Drugs in Coming Years -- Update (https://www.marketwatch.com/story/wegovy-make ...)
Related News
Sep 21 2026, 11:27
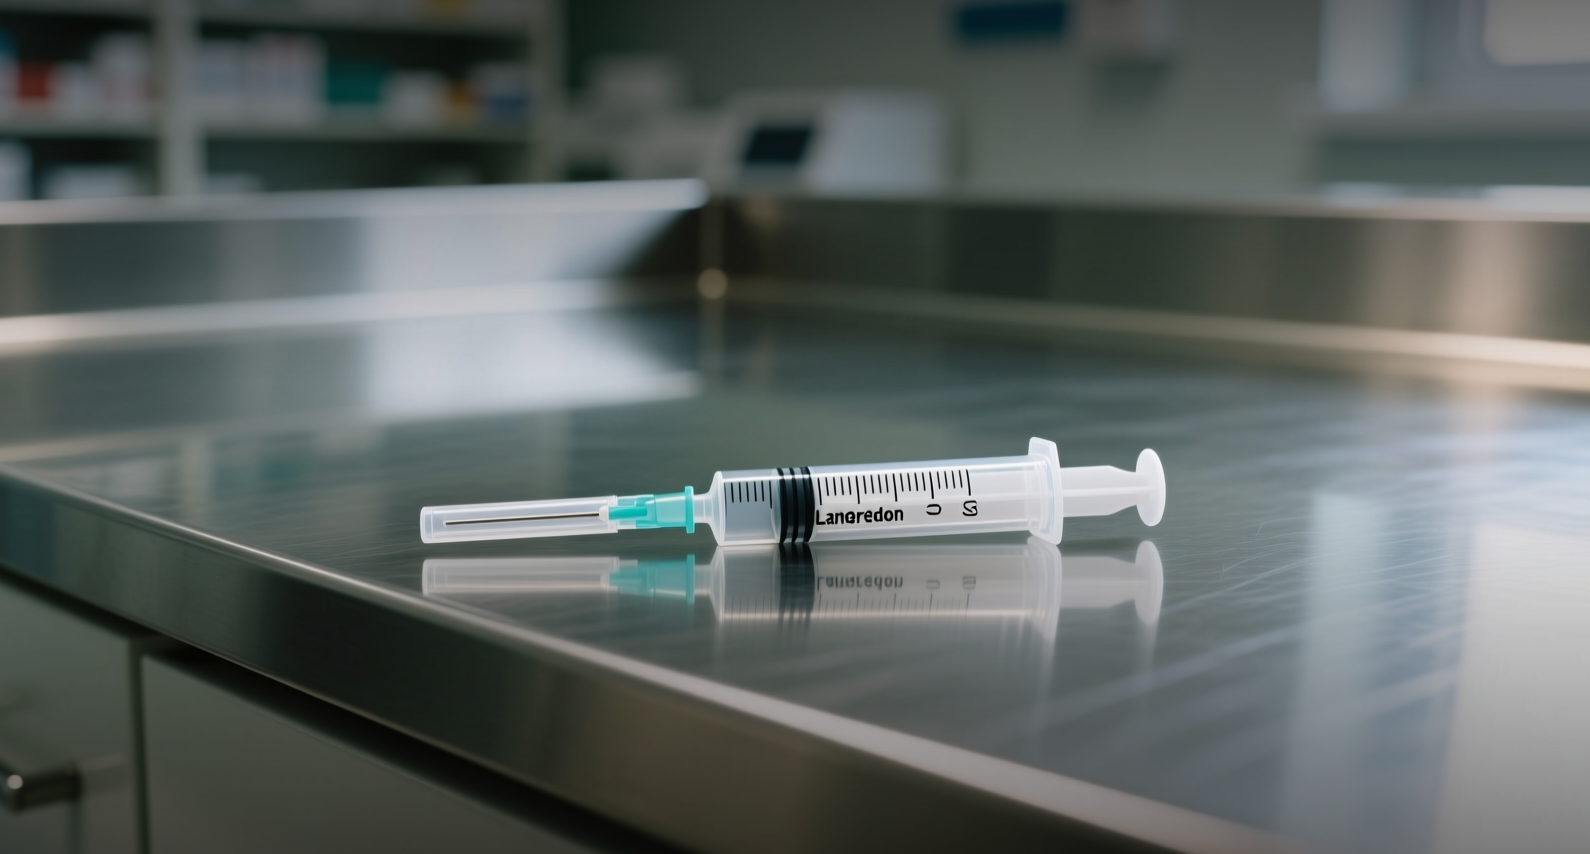
Ipsen falls 6.9% as early US generic ends Somatuline exclusivity
Ipsen lost 6.9% in Paris trading, closing at €145.20, after Amneal Pharmaceuticals secured FDA clearance for a copy of the French drugmaker's top-selling hormone therapy and began selling it the same day. The approval, disclosed by Amneal on Friday evening, covers a prefilled, single-dose sterile syringe carrying the FDA's competitive generic therapy designation. It is cleared for acromegaly, advanced gastroenteropancreatic neuroendocrine tumors and carcinoid syndrome — the same three indications Somatuline holds. "The challenges will not disappear with the generic's entry into the market," Jefferies analysts wrote, maintaining an Underperform rating and a €135 price target. The bank said the launch is already reflected in 2026 forecasts but poses a risk to 2027 expectations, particularly if weekly launch data come in strong. Somatuline generated $983 million in US sales in the 12 months ended July 2026, according to healthcare data provider IQVIA. The drug accounted for roughly 30% of Ipsen's total revenue in the first half of 2026, making it the single largest contributor to the company's top line. Ipsen's market capitalization stood at €14.66 billion after Monday's decline, with the stock down 8.8% over five sessions. Amneal said it holds dedicated, large-scale in-house manufacturing capacity for the lanreotide product, a detail that matters for a long-acting injectable where supply reliability determines how quickly pharmacies and clinics switch. RBC Capital analysts said the generic's approved dose represents about 60% of Somatuline volume, according to IQVIA data. The Canadian bank called the launch timing broadly in line with expectations and said Ipsen's guidance already factors it in, keeping an Outperform rating and a €148 target. The longer-term risk sits beyond the generic. Jefferies flagged that if Camurus's CAM-2029 study shows its product is superior to Somatuline, consensus profit estimates for 2028 and 2029 could fall by about 10%. Ipsen's oncology franchise accounted for 69.2% of net sales at the end of 2025, with neuroscience at 20.3% and rare diseases at 10.5%, leaving limited near-term offsets to a Somatuline decline. For holders, the sell-off reprices a franchise that has carried Ipsen's earnings rather than a one-quarter miss, and the €135-to-€148 analyst range now brackets the current price. The next test is Ipsen's third-quarter sales release on Oct. 15, when management will have to address whether US Somatuline volumes are holding and whether full-year guidance still stands. This article is for informational purposes only and does not constitute investment advice.
Sep 21 2026, 11:27
Goolsbee sets a demand-cut bar of 2% inflation for rate cuts
Rate cuts now require weaker demand, not just slower price growth, Chicago Fed President Austan Goolsbee said, describing an economy in which supply disruptions arrive in sequence rather than one at a time. "The response need not replicate the playbook used for demand shocks," Goolsbee, a 2027 FOMC voter, said. He added that restoring price stability "will not be painless," that the Fed faces a tradeoff between inflation and unemployment, and that ignoring recurring shocks "would be a dereliction of duty" on price stability. The remarks land against a fed funds target range of 4.00% to 4.25%, set after the 25 basis point cut in September 2025, with the Fed holding at the two subsequent meetings. The Fed's preferred inflation gauge, the core PCE price index, has run above the 2% target for more than four years. Goolsbee's conditionality — that the Fed "must see credible evidence supply shocks are receding" — is the operative sentence for markets, because it converts the cut debate from a question of how fast demand cools into a question of whether the shocks themselves fade. Central banks normally "look through" supply shocks, treating a one-off energy or shipping disruption as something that drops out of the 12-month comparison on its own. Goolsbee's argument is that this habit breaks down when shocks arrive in sequence rather than in isolation, because each new shock resets the price level before the prior one has washed out. That is the mechanism behind his demand-reduction prescription: if the supply side keeps re-inflating, only the demand side can close the gap. The transmission chain runs through the front end of the curve first. Two-year Treasury yields, the maturity most sensitive to the expected path of policy, sit near 3.55% after falling through the autumn on easing expectations; a demand-reduction framing argues against pricing further cuts on the strength of softening activity data alone. The dollar has traded in a narrow band around 99 on the DXY index, and gold near $4,200 an ounce has held a bid that reflects the same inflation-persistence premium Goolsbee is describing. The S&P 500 has continued to grind higher on earnings, but rate-sensitive sectors — utilities, real estate, small caps — have lagged the index, a divergence that widens if the cut timeline extends. The last time a Fed official used language this close to "not painless" was in the 2022-2023 tightening cycle, when Chair Jerome Powell warned of "pain" in the labor market and the Fed ultimately took the funds rate from near zero to 5.25%-5.50% over 16 months. Unemployment rose from 3.5% to a peak of 4.3% in July 2024 before settling back near 4.2%, and core PCE fell from a 5.4% peak to roughly 2.7% — a disinflation that took more than two years and cost a measurable amount of employment. Goolsbee's framing implies a similar willingness to accept that cost again if the shocks persist. What that means for positioning is a higher hurdle, not a closed door. Futures markets have repeatedly priced the first cut earlier than it arrived, and each repricing has hit the same assets: two-year yields up, the dollar firmer, rate-sensitive equities and long-duration growth names under pressure. The practical read is that a soft payrolls print alone will not be sufficient evidence. Goolsbee's test requires visible progress on the supply side — energy prices, freight rates, goods inflation — and until that shows up in the data, the burden of proof sits with the doves. The next FOMC meeting is scheduled for December 9-10, with the statement and updated projections due at 2 p.m. Eastern. Between now and then, the releases that matter most for Goolsbee's test are the monthly CPI and PCE prints and the ISM manufacturing prices-paid index, which tracks input costs before they reach consumers. If those series keep re-accelerating, the demand-reduction argument gains internal support and the cut timeline extends into the second half of 2026. If they cool for two or three consecutive months, Goolsbee's own conditionality gives the committee room to move — which is precisely why he wrote it as a condition rather than a commitment. This article is for informational purposes only and does not constitute investment advice.
Sep 21 2026, 11:25
Lumentum jumps 4.2% on heavy volume with no catalyst confirmed
Lumentum Holdings shares climbed 4.2% in the prior session on trading volume above the stock's recent average, a move that arrived without any company filing, guidance update or contract announcement to explain it. The advance left the optical component maker's rally resting on order flow rather than news. No earnings release, customer win or transaction was disclosed around the session, and the company has not issued a statement addressing the gain. "Price action without a disclosed catalyst is a positioning event, not a fundamental one," said Priya Mehta, an equity market structure analyst who tracks fund flows and options positioning. "The question is whether the volume that produced the move shows up again tomorrow, because that is what separates a one-day squeeze from a re-rating." Volume was the distinguishing feature of the session. The gain came on turnover above the stock's recent average, the kind of participation that typically reflects institutional accumulation or options-related hedging rather than retail drift. Lumentum did not disclose a specific volume figure, and the company's next scheduled earnings release has not yet been dated. The move also ran against the read on earnings estimates. The recent trend in revisions to Lumentum's consensus numbers has been cited as unlikely to support further near-term price gains, which puts the stock's advance at odds with the direction analysts have been marking their models. That divergence matters because Lumentum trades as part of a small optical and photonics cohort whose members move together on shared demand signals from cloud and data-center customers. Coherent, Fabrinet and Ciena are the closest listed comparables, and each has traded on the same hyperscaler capital-spending narrative that drives Lumentum's transceiver and laser business. A single-name move of this size without a sector-wide trigger is unusual for the group. ## What the volume says that the estimates don't For a portfolio manager holding Lumentum, the practical question is whether the 4.2% gain represents the start of a repricing or a liquidity event that fades. The two are distinguishable by what happens next: a genuine re-rating tends to hold its gains on declining volume as sellers step back, while a flow-driven spike often gives back the move once the buying pressure exhausts. The estimate revision trend is the counterweight. When consensus numbers are drifting lower or holding flat, rallies in high-beta semiconductor supply-chain names tend to be shorter-lived, because there is no upward revision cycle to anchor a higher multiple. Lumentum's exposure to data-center transceiver demand ties it directly to hyperscaler capital expenditure plans, which are set on quarterly calls rather than daily news flow. Traders will watch three things over the coming sessions: whether volume stays above average on any follow-through advance, whether any sell-side firm publishes a revised price target or rating on Lumentum, and whether the optical peer group confirms the move with gains of its own. Absent at least one of those, the 4.2% gain looks like a positioning event confined to a single ticker. The broader semiconductor complex provides the backdrop. Lumentum's fortunes are tied to the same AI infrastructure buildout that has driven demand for optical interconnect, and any shift in hyperscaler spending commentary would move the stock far more than a single session of elevated volume. Until a fundamental datapoint arrives, the stock's direction rests on flows. This article is for informational purposes only and does not constitute investment advice.